Fast Bayesian Calibration of Option Pricing Models Based on Sequential Monte Carlo Methods and Deep Learning
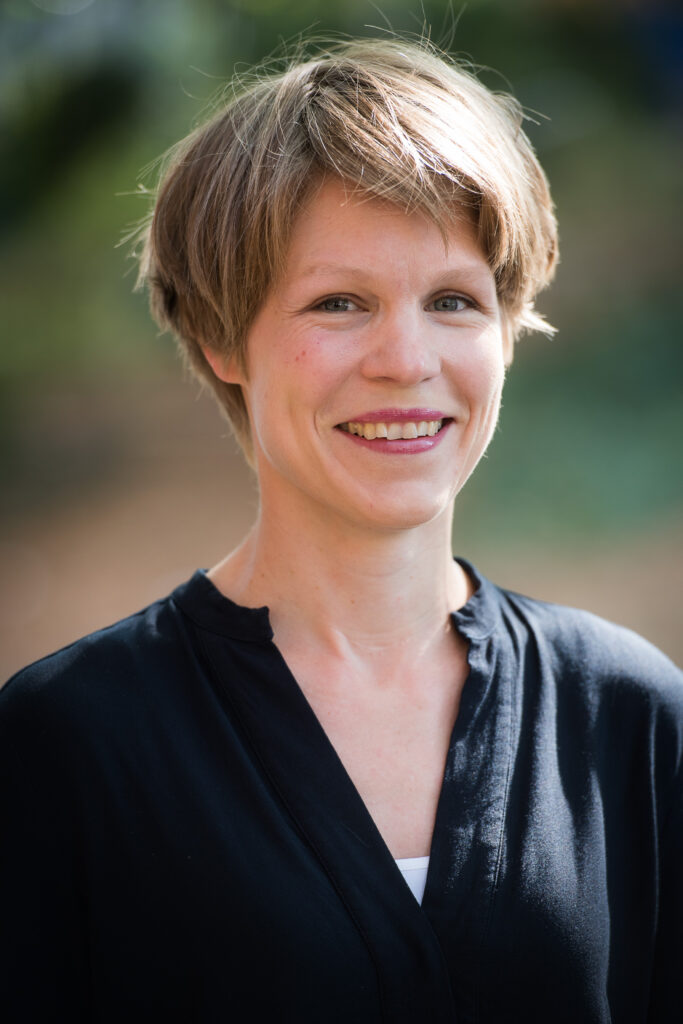
Speaker: Prof. Dr. Eva Lütkebohmert-Holtz
Time: 15:00 (GMT), October 28, 2026
Abstract
Model calibration is a challenging yet fundamental task in financial engineering. Using sequential Monte Carlo methods, our speaker Prof. Dr. Eva Lütkebohmert-Holtz reformulates the non-convex optimization problem as a Bayesian estimation task. This allows to compute any statistic of the estimated parameters, mitigating the strong dependence on starting points and avoiding the troublesome local minima, that plague standard calibration methods. To accelerate computation, she incorporates Markov Chain Monte Carlo methods with delayed acceptance and a neural network-based option pricing approach. When applied to S&P 500 index options, her Bayesian algorithms significantly outperform the standard approach in terms of runtime, accuracy, and statistical fit.
Our Speaker
Eva Lütkebohmert-Holtz is Professor for Quantitative Finance at the University of Freiburg. She studied mathematics at the Universities of Bonn and Toronto and received her PhD in Mathematics from the University of Bonn in 2004. From 2005-2006 she has been working as research analyst for the Deutsche Bundesbank in the Department for Banking Supervision. From 2006-2009 she was Juniorprofessor at the Faculty for Economics and Social Sciences at the University of Bonn. Afterwards she switched to the University of Freiburg as head of the junior research group “Financial Mathematics: Pricing of Risks in Incomplete Markets”. In 2013 she was announced Professor for Quantitatitve Finance. Since 2025 she is dean of the Faculty of Economics and Behavioural Sciences at the University of Freiburg.
Her research covers both the theoretical and empirical analysis of financial markets and lies at the intersection of economics, mathematics und statistics. Eva Lütkebohmert-Holtz published various articles on the management and modelling of financial risks, in particular credit and liquidity risk, on interest rate markets, as well as on the valuation and hedging of financial derivatives.